


The duration mismatch between assets and liabilities is a well-documented problem. Banks are the most obvious example, but evergreen funds are not insulated from the same risk.
And yes, the 5% redemption caps in semi-liquid funds are in place to protect capital by avoiding fire sales. But we’ve already seen examples where the redemption queue does not clear after a few quarters, and forces the manager’s hand. Remember Bluerock?

Today, I’ll make the case for why private credit is not going to be the undoing of evergreen structures. And why private equity (where redemptions are currently running low) might be.
The Big Picture
The redemption headlines center on evergreen private credit funds. Requests are up across the board, with many managers capping outflows per their prospectus provisions.
👉 Everything you wanted to know about gating provisions across different fund structures:

What's interesting: private credit funds are experiencing redemption pressure. Private equity funds? Not so much.
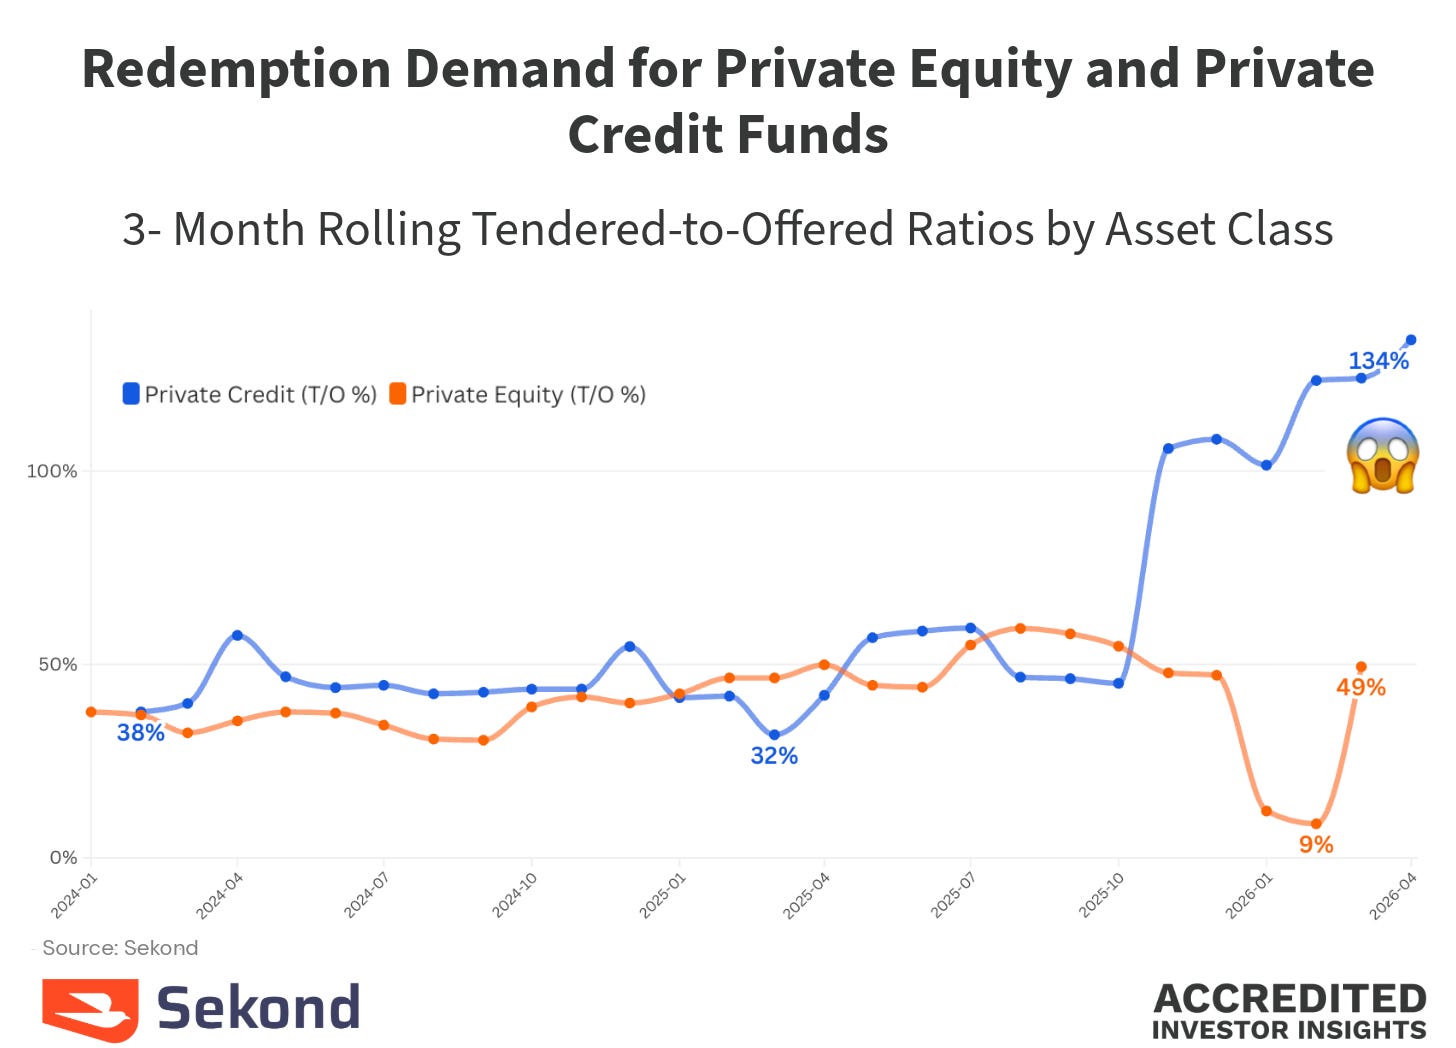
Side note: You access Sekond’s redemption tracker (LINK). It’s free with a Sekond account. And no, I’m not paid to promote it, I just really like data.
Why Private Credit Can Handle This
I recently attended an event where Mark Rowan of Apollo was presenting. His take on evergreen private credit funds was blunt: it would take a very incapable manager to fail to meet the 5% quarterly redemption cap.
I wholeheartedly agree. And the data proves it.
I pulled financial statements for four of the largest private credit evergreen funds: Blackstone Private Credit (BCRED), Cliffwater Corporate Lending, Blue Owl Credit Income, and HPS Corporate Lending.


I then compared them to four large evergreen PE funds: Partners Group PE, Blackstone Private Equity Strategies, KKR Private Equity Conglomerate, and AMG Pantheon.

Here’s what embedded liquidity actually looks like:
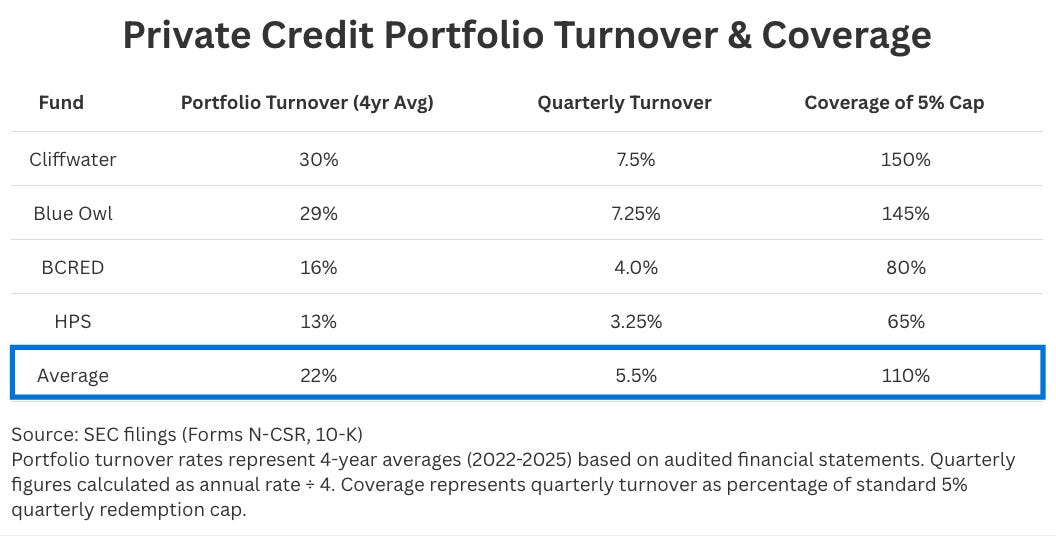
🗝️ The key point: this is actual cash coming back from loans that matured or refinanced. These funds generate 65-150% of the quarterly redemption cap from portfolio turnover alone. They don’t need to sell assets at distressed prices. They just need to not reinvest some of what’s organically maturing.
Your average middle-market loan has a duration of 5 years. That means ~20% of a mature portfolio pays off annually (or ~5% quarterly, how’s that for some easy math?) The funds with higher turnover (Cliffwater at 30%, Blue Owl at 29%) are generating 7-7.5% quarterly in maturing loans, or 45-50% more liquidity than the maximum allowed redemptions.
Even the fund with the lowest turnover (HPS at 13%) generates 3.25% quarterly from loan maturities, covering 65% of the redemption cap from organic activity alone.
The Income Cushion
There’s another important dynamic working in private credit’s favor: cash income cushions declines in valuations of the underlying portfolio.
That income is generally distributed to investors rather than retained for redemptions, but it still matters (optically). Investors who see positive returns don't redeem. And funds can post positive returns even when marks decline:
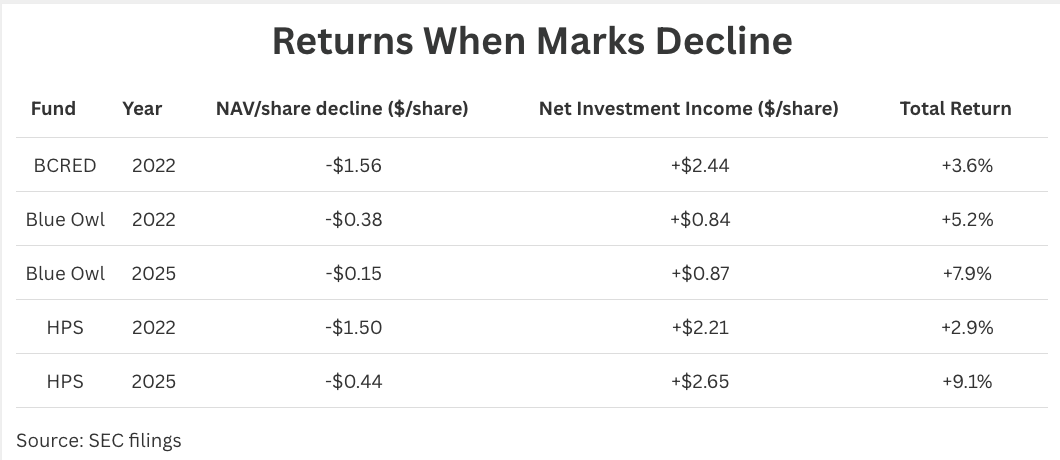
Not a single fund posted a negative return in the years when marks declined in this sample set. The 10% annual cash yield absorbed 4-6% mark declines and still produced positive returns.
Happy investors don’t redeem. When private credit funds maintain positive returns through stress periods, redemption requests stay manageable. And with evergreen funds, keeping redemption requests manageable is half of the battle. The organic portfolio turnover can handle the modest outflows without forcing asset sales.
Two important caveats: first, watch the source of distributions. Funds can distribute more than they earn (return of capital). Second, high DRIP participation helps any fund manage redemptions (investors reinvest distributions rather than taking cash).

Compare that to private equity: when marks decline, there’s no income cushion. Returns go negative. That’s when redemption requests spike, just as liquidity dries up. Let me show you how this plays out next.
Why Private Equity Can’t
Now let’s talk about private equity, where redemption requests are currently running low, and where everything looks fine. Until you look at the cash flows.
Behold the four largest evergreen PE funds. Here's what should keep you up at night:
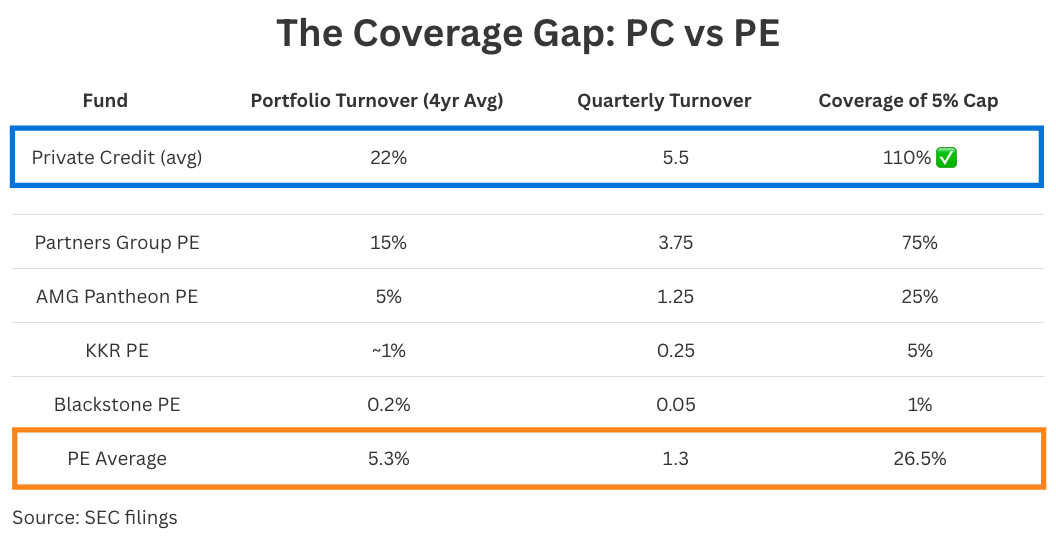
Private credit funds cover 65-150% of the redemption cap from portfolio turnover. Private equity? The best fund covers 75%. The others: 1-25%.
Best Case
Partners Group has the highest portfolio turnover in our sample (15%) and is actually generating cash from exits. In the six months ended September 2025, they received $1.08 billion from portfolio sales while deploying $917 million. Net cash inflow from the portfolio: $165 million.
That 15% turnover covers 75% of the quarterly redemption cap. Impressive for private equity.
But compare to private credit:
Worst PC fund (HPS): 13% turnover + 10% NII = 5.75% quarterly liquidity = 115% coverage
Best PE fund (Partners Group): 15% turnover + negative NII = 3.75% quarterly liquidity = 75% coverage
Private credit’s worst beats private equity’s best.
➡️ And here’s the irony: Partners Group’s 75% coverage is being stress-tested right now. In the six months ended September 2025, redemptions hit $1.3 billion (an annualized rate of 16% of NAV).
How are they handling it? By selling investments ($1.08 billion in proceeds), borrowing $711 million from their credit facility, and raising what new capital they can ($504 million, which covered less than half of redemptions).
Now imagine the same redemption pressure hitting the other three funds.
Blackstone Private Equity Strategies Fund
2025 performance:
Net increase in net assets: $370M (looks great!)
Where it came from: $381M unrealized appreciation (103% of the return)
Net investment loss: -$12M (that’s a minus sign in front)
Realized gains from portfolio sales: $0
The cash flows:
Raised from investors: $1.455B
Deployed into underlying PE fund: -$1.442B (This is a feeder fund, it doesn't own companies directly, it owns units in Blackstone's master PE fund, BXPE)
Proceeds from underlying PE funds: $6.3M
The underlying fund returned $6.3 million against a $3.2 billion portfolio. Portfolio turnover: 0.2% annually.
At this rate, it would take 500 years to liquidate the portfolio through natural exits. Yes, this is a recent vintage fund. But PE portfolios don’t generate cash for years, until they do, all at once.
💰Cash on the balance sheet: $304,000.
Not $304 million. Three hundred and four thousand dollars against $3.1 billion in net assets.
Current redemptions are manageable ($7.8M in 2025, up from $236K in 2024). But what happens if they hit 5% of NAV?
New capital raising is the playbook for the entire PE evergreen universe right now. And guess what? Capital raising is highly correlated to returns.
The PE Treadmill
Partners Group aside, here’s what the deployment picture looks like for the other three funds:
Blackstone PE: $1.442B deployed, $6M returned = 241:1
KKR PE: $3.849B deployed, $78M returned = 49:1
AMG Pantheon: $696M deployed (6mo), $0 returned = ∞
They're not building liquidity cushions. Cash creates drag on returns, so managers maximize deployment, which works perfectly until fundraising slows or redemptions spike.
➡️ Here’s what should really concern you: every single PE fund reported 80-109% of returns from unrealized appreciation.
Partners Group (the one actually showing realized gains) still showed 101% of returns from marks. Realized gains were 15% of the total, offset by negative net investment income.
The other three? Same story. 80-109% unrealized gains. Near-zero realized gains. But unlike Partners Group, they’re not selling anything to validate those marks. Unrealized gains are paper returns.
“Cash from operations”, you ask? They’re consuming it through fees and expenses.
Compare that to private credit, where portfolio companies are returning ~20% of the portfolio annually through loan maturities, and the funds generate 10% annual cash yields from interest payments.
How Long Will It Last?
Private equity evergreen funds are running a perpetual fundraising machine. The model works beautifully when:
Fundraising remains strong (covers redemptions + deployment)
Redemptions stay low (currently the case)
Marks keep going up (“number go up” is the investment thesis here).
It doesn’t work so well when any of the above reverse.
Look at what happened to these four PE funds in 2025:
Partners Group: raised $504M in 6 months, paid $1.312B in redemptions (used portfolio sales + $711M in borrowing to cover the gap)
Blackstone PE: raised $1.455B, deployed $1.442B (99%), cash declined to $304K (“K” as in thousands)
KKR PE: raised $4.184B, deployed $3.849B in acquisitions, received $78M back (net deployment 90%), generated $35M in realized gains vs. $1.127B in unrealized gains
AMG Pantheon: raised $705M in 6 months, deployed $696M (99%), cash declined $100M despite massive fundraising
The playbook is beautifully simple: raise $→deploy$ → mark up investments → show great returns. Nobody is building cash reserves, they are barely keeping pace with deployment. And nobody is showing any meaningful realized gains, either, so we don’t actually know what these portfolios would fetch in a sale.
Private credit, by contrast, has embedded liquidity: loans mature, borrowers refinance. Cash comes back at (somewhat) predictable rates (whether or not new investors show up).

What We Don't Know
We don’t really know what happens when private equity evergreen redemptions accelerate. We don't know how PE portfolios will be valued in a real down market: these marks haven't been tested by forced sales. And we don't know which funds will maintain fundraising when returns turn negative.
The same is true for private credit in a genuine credit crunch: who will be the lender of last resort if the entire PC universe contracts? We don’t know.
➡️ What we do know is this: private credit has organic liquidity (at least, right now). Portfolio turnover of 13-30% annually provides 3-7.5% quarterly cash from maturities.
Private equity has no such natural liquidity. Portfolio turnover of 0.2-15% (average 5.3%) provides 0.05-3.75% quarterly cash from exits. Net investment income is negative across the board. Average coverage of the redemption cap: 26.5%.
Even the best PE fund (Partners Group at 75% coverage) falls short of the worst private credit fund (HPS at 122% coverage). And Partners Group is the outlier, as one of the oldest vintage evergreen PE funds with some of the most mature portfolio companies.
One of these is well-suited for an evergreen structure with quarterly redemptions. The other is a liquidity dumpster fire waiting for a match.
What to Watch
Cash-to-NAV ratio. Below 5% is concerning. Below 1% is alarming.
Proceeds from sales of investments. Look at the cash flow statement. Are investments being sold?
Realized vs. unrealized gains. What percentage of reported returns are marks vs. actual exits? Unrealized gains = paper returns. (Spoiler alert: most funds show mostly unrealized gains).
New capital vs. redemptions. Track the trend. If fundraising slows while redemptions increase, the gap closes fast. These funds have almost no margin for error.
For private credit funds, watch the same metrics, but the thresholds are much higher because portfolio turnover provides a massive cushion.
For private equity, there is no cushion on the fundraising treadmill. Just make sure you don’t end up like this:
-Leyla
P.S. If you are new here, you’ll find all of our content somewhat sorted and somewhat organized here:

When the music finally stops, I hope some of these evergreen PE funds consider listing as exchange listed closed end funds (CEFs) to compete with VCX, DXYZ, RVI, PWRL, and CFND. Sure, many CEFs trade at discounts to NAV, so investors may not be thrilled about a conversion. But if the next market downturn ends up creating a healthy listed private equity market in the US, similar to the UK's ecosystem with Scottish Mortgage, HarbourVest Global Private Equity, Pantheon, and 3i group etc, I think that would be a win for retail investors.
From a liquidity‑engineering standpoint, where would you place private real estate evergreen funds in your hierarchy? They generate NOI but not principal return, so I’m wondering whether you view them as structurally closer to PE or as a distinct middle‑liquidity asset class.